Business
Tinubu Signs Deep-Offshore Tax Remission Order: What Nigeria's $50bn Target Means
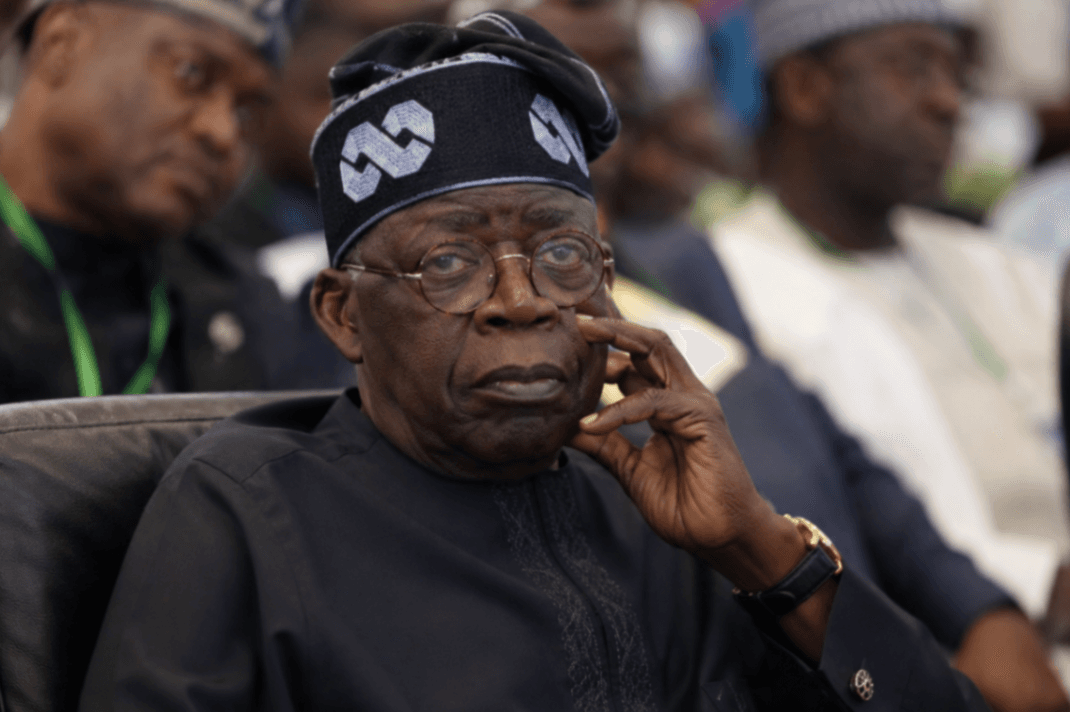
President Bola Tinubu has approved Nigeria's deep-offshore tax-remission framework. Officials say it could unlock up to $50 billion in investment, but that figure is potential, not committed capital.
What happened
President Bola Ahmed Tinubu approved Nigeria's new deep-offshore incentive framework through the Deep Offshore Oil and Gas Projects Incentives (Tax Remission) Order, 2026 (S. I. No. 37 of 2026). The order is dated 6 August 2026 and published in Federal Republic of Nigeria Official Gazette No. 150 of 10 August 2026.
Government officials say the framework could help unlock up to $50 billion in deep-offshore investment.
That $50 billion is a potential investment figure, not money already committed to Nigeria.
What the order actually changes
The order sets clear tax-credit rules for qualifying deep-offshore projects instead of ad hoc project-by-project negotiations.
According to the order: For qualifying oil projects, the Standard Production Tax Credit can be US$3.00 per barrel (or 20% of fiscal oil price, whichever is lower) up to cumulative production of 150 million barrels, where reserves do not exceed the relevant 400 million barrel split.
In practical terms: Smaller qualifying reserve bands get a lower standard credit rate, capped by both price and volume limits.
According to the order: A higher standard band can be US$4.50 per barrel (or 20% of fiscal oil price, whichever is lower) up to 500 million barrels cumulative production, where reserves exceed the 400 million barrel split condition.
In practical terms: Larger qualifying developments can access a higher standard credit, but still under defined ceilings and thresholds.
According to the order: There is an additional US$1.00 per barrel Standard PTC provision for qualifying leases under the relevant paragraph 1(1)(b) category.
In practical terms: Some qualifying lease categories can receive an extra per-barrel uplift within the order's structure.
According to the order: If fiscal oil price for a month falls below US$50 per barrel, applicable credit rates for that month are reduced to 50%.
In practical terms: The framework contains a downside safeguard so incentive value adjusts in lower-price periods.
According to the order: Standard plus Supplementary PTC cannot exceed US$11.50 per barrel for oil projects, and US$8.00 per barrel of oil equivalent for non-associated gas projects.
In practical terms: Even where supplementary credits apply, there is a hard combined ceiling.
According to the order: For qualifying non-associated gas, the Standard PTC includes US$1.00 per thousand standard cubic feet or 30% of fiscal gas price (whichever is lower), and a lower US$0.50 per thousand standard cubic feet band under the higher HCL range, with HCL-based limits.
In practical terms: Gas incentives are structured and conditional, not open-ended.
According to the order: A Profit Oil Reset can apply to eligible deep-offshore developments, with reset commencement at 70:30 for contractor-government allocation, and the eligible development must be ring-fenced for cost recovery and tax purposes.
In practical terms: Eligible projects can be treated as distinct developments for fiscal progression, but only within strict conditions.
According to the order: Tax credits under this regime are not refundable, transferable, assignable, saleable, or convertible to cash.
In practical terms: The incentives are tax-relief mechanisms, not cash grants.
Who can benefit
Eligibility is conditional. The order links qualifying treatment to project category and timing, including the FID window for relevant existing-lease categories up to 31 December 2029.
The order also sets application and review requirements, including open-book style project economics for supplementary requests and Service consideration of complete applications within 45 days.
Why government is offering these incentives
State House material frames the policy as an effort to improve investment certainty for capital-intensive deep-offshore projects and make Nigeria more competitive for globally mobile upstream capital.
The policy direction is to move from case-by-case bargaining toward a rules-based framework with defined eligibility, processes, and ceilings.
What Nigeria could gain
If investors proceed with qualifying projects, Nigeria could see higher capital inflows, more offshore project activity, additional production over time, and wider effects across supply chains and services.
Those outcomes are potential, not automatic.
What Nigeria could give up
Tax incentives can improve project economics for investors, but they may also reduce the immediate fiscal take from qualifying output compared with a no-incentive scenario.
The policy trade-off is clear: attract investment and project execution while protecting long-term national value through eligibility controls, ceilings, and safeguards.
The $50 billion question
The $50 billion headline should be read as potential investment size, not committed capital.
Potential investment: a policy estimate of what could be unlocked if projects qualify and proceed.
Announced investment intentions: statements by officials or companies about possible future spending.
Committed capital: board-approved, financed project spending tied to actual FIDs and execution plans.
Actual spend: money disbursed during construction and development.
The final test is whether projects reach FID, move into construction, and spend capital in practice.
Bonga Southwest
State House releases link the incentive push to Shell's proposed Bonga South West development and broader deep-offshore project momentum.
State House also carries Shell-related statements describing potential investment around $20 billion if the project reaches FID. Reuters also reported on potential Bonga South West investment progress.
These are projections and potential outcomes, not guaranteed results.
What remains uncertain
The incentives do not by themselves guarantee final investment decisions, construction start, production levels, jobs, foreign-exchange inflows, or government revenue outcomes.
Execution risk remains: project economics, partner decisions, timing, and implementation quality will determine what happens next.
What Nigerians should watch next
- How quickly implementation steps under the order are operationalised.
- Which projects actually qualify under the published criteria.
- How many eligible projects reach final investment decision.
- Whether announced plans convert into committed and then deployed capital.
- Construction progress and delivery timelines on qualifying projects.
- When additional production starts and how sustainably it is maintained.
- How government revenue outcomes compare with policy expectations over time.
Sources
- Official Deep Offshore Order (State House PDF)
- State House: Deep-offshore framework and $50bn potential
- State House: Bonga South West targeted incentives
- State House: Shell CEO statement and potential investment
- Reuters corroboration: Nigeria deep-water framework report (via Google News item)
- Reuters corroboration: Bonga South West potential investment report (via Google News item)
Tags
PUBLISHER NOTE
About Talk Ya True
Talk Ya True publishes independent reporting and analysis with clear attribution, source transparency and corrections when needed.
Related Articles
Africa
Nigeria Halts Parliamentary Engagements With South Africa Amid Rising Xenophobic Violence
Nigeria
FG to Give 5 Million Nigerian Students 100MB Free Daily Data From October
Politics
Remi Tinubu Honoured as Oso Di Eme I in Imo as South-East Visit Sparks 2027 Debate
Politics
Atiku, Obi and Makinde Hold Firm as Opposition Struggles for One 2027 Candidate
Stay Informed
Get the latest stories from Nigeria.
Free news updates. Unsubscribe anytime.
By subscribing, you agree to receive free news updates from Talk Ya True. You can unsubscribe at any time.